August 2026 Nickel & Surcharge Update

Monthly Nickel and Surcharge Update
August 2026 Update
Thanks for reading the Ram Alloys Monthly Nickel and 316L s/c update, intended to help our valued customers make educated business decisions.
Thanks for reading the Ram Alloys Monthly Tariff, Nickel, and 316L s/c update, intended to help our valued customers make educated business decisions.
THE ACTIVE REMAINING (2) TRUMP TARIFFS
- Steel War: INCREASED TO 50% Section 232 Tariff on all COPPER, Steel and Aluminum
- Validity NOT subject to upcoming Supreme Court Ruling
- Began March 12th - Original Tariff = 25%
- Quotas Eliminated. Exemption Process Terminated
- Excluded and separate from SUPREME COURT Trade War Reciprocal Tariffs
- June 4th: Tariff Rate Raised to 50%
- Except for UK - remains 25% while they negotiate (still negotiating)
- Tariffs for "derivatives" of steel and aluminum remain difficult to analyze, as either reciprocal or Section 232 tariffs apply, but the method for applying either is unclear
- August 1, 2025: Copper added to the 50% Section 232 tariffs, along with steel and aluminum
- New Forced Labor Tariffs - Section 301
- Replaced Section 122 Tariffs
- President Trump’s Office of the U.S. Trade Representative enacted new tariffs ranging from 10 to 12.5% on 80 countries and the European Union based on an investigation into forced labor under Section 301 of the Trade Act of 1974.
- The new measures are framed as a response to uneven enforcement of forced labor import bans, with the administration arguing that inconsistent enforcement allows low-cost goods made with forced labor to undercut U.S. workers.
- Currently being sued by 25 States for its validity.
- Notable Countries with Tariff Changes:
- 10% Tariff - European Union, India, Mexico, Taiwan , United Kingdom, etc.
- 12.5% Tariff - Japan, South Korea, Switzerland
THE THREATENED TRUMP TARIFFS
- BRICS Tariff (threatened)
- President Trump's has been quiet on this front for some time, but the original 100% threat may be resurrected after losing the SCOTUS battle
- Meaning, application, interpretation, impact, etc.
- BRICS of course stands for: Brazil, Russia, India, China, and South Africa
- Other members include Saudi Arabia, Egypt, Iran, Ethiopia, the United Arab Emirates, and Indonesia
- BRICS Partner Countries: Belarus, Bolivia, Cuba, Kazakhstan, Malaysia, Nigeria, Thailand, Uganda, Uzbekistan, and Vietnam
- Reciprocal Digital Tax Tariffs (threatened)
- President Trump is threatening to impose a 100% tariff on countries that levy a tax on U.S. companies offering digital services.
- A new U.S. tariff on other nations' imports would override any trade agreements with a trading partner, Mr. Trump noted, adding that the 100% import duty would be imposed immediately if a country proceeds with a digital services tax.
- European Union and the U.S. to finalize a trade deal that caps tariffs on most EU exports at 15%, DOES NOT include Digital Taxes, still at a deadlock.
THE EXPIRED OR OVERRULED TRUMP TARIFFS
- Drug War Tariffs
- Reciprocal Tariffs
- Section 122 Tariffs
Reciprocal Tariff Legal
Update U.S. v Iran Conflict News Section 232 New Guidance
|
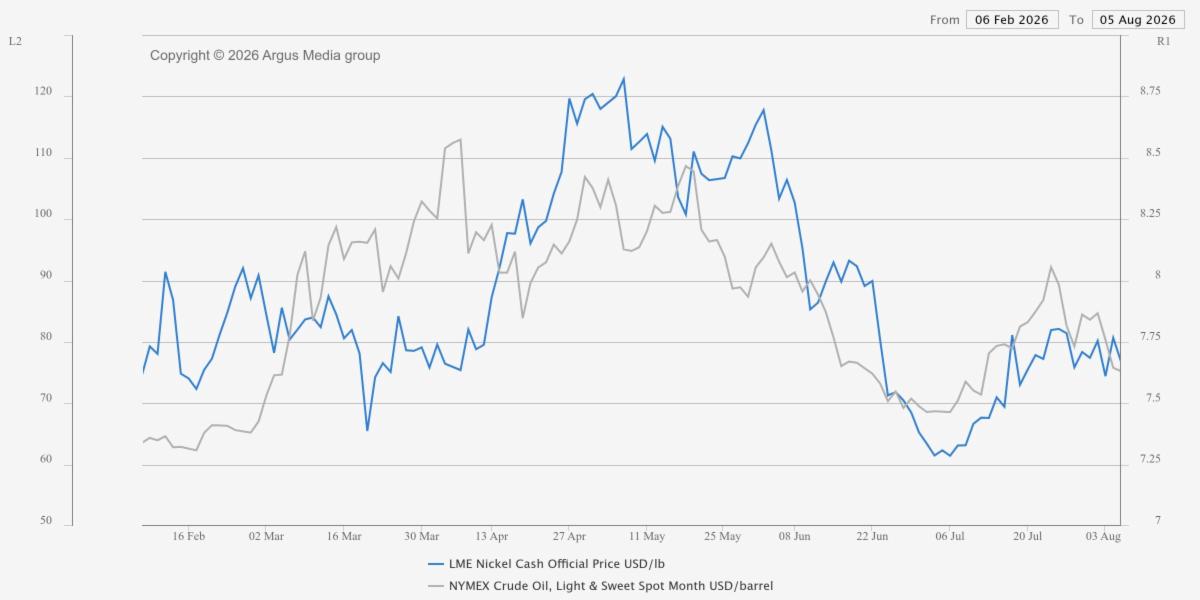
U.S v Iran Conflict The ongoing U.S.–Iran conflict continues to shock global crude markets, due to disruptions to the Strait of Hormuz—a critical shipping route that carries roughly 20% of the world’s oil. Why is this important? Commodity prices, specifically nickel, track oil prices (SEE MIDDLE CHART BELOW). Additionally, the Middle East region accounts for ~25% of global sulfur production, which is a critical ingredient for nickel refining. As such, expect a future increase! NEWEST DEVELOPMENT: As of 8/05/2026, The U.S.–Iran conflict remains highly volatile, but recent developments suggest both sides are pursuing diplomacy while continuing to prepare for possible escalation. Negotiations involving Iran, Oman, and the United States are focused on reopening the Strait of Hormuz, with officials indicating that a framework for an agreement may be close, although key disputes, such as maritime control and security arrangements, remain unresolved. At the same time, President Trump has warned that military action could resume if talks fail, while Iran has threatened retaliation against U.S. forces and Gulf energy infrastructure in the event of new strikes. As always, this situation is extremely volatile and could change by the hour, so stay updated for the newest development!! In other words, "Well, it's groundhog day...again" - Phil (Bill Murry) Section 232: New Guidance On April 6th, the government published new Section 232 guidance, mostly concerning derivatives, metals classifications, changes in country of origin application, etc. Bad news, nothing changes regarding the Steel War Tariffs, which remain 50% on all Copper, Steel and Aluminum. |
Current Take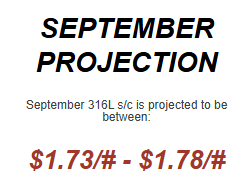
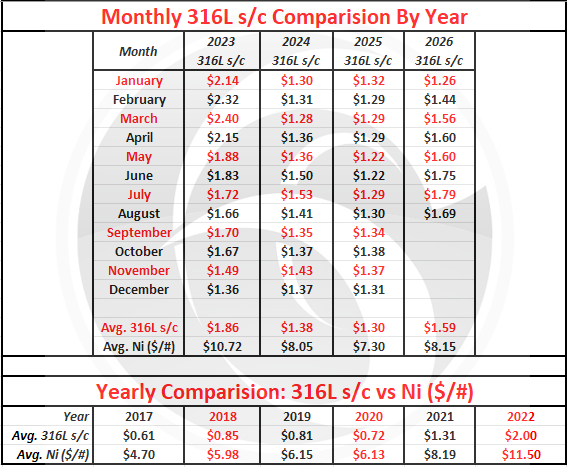
RAW MATERIAL PRICES: August's 316L surcharge decreased for the first time since since January. Although Molybdenum increase due to greater stainless steel demand and supply tightness, the s/c was hit hard by expected decreases in Nickel and Energy.
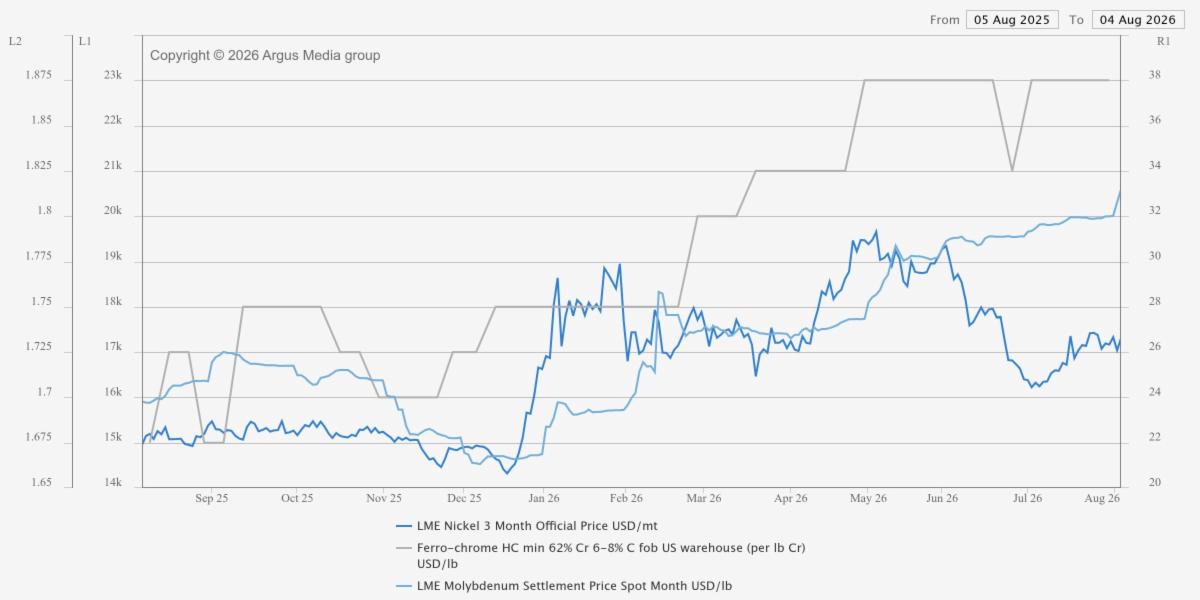
The drop in Nickel pricing was predicted (Indonesian supply cuts) but not to this extent, decreasing $0.10/LB. However, expect September mirror July, as commodity prices are on the rise. Molybdenum's run is expected to continue, approaching a 41 month high. Chromium has remained consistent, possibly dropping in the future. While Energy slightly dipped, the Iranian war may drive future gains.
Will all commodities rising, the September surcharge is expected to sharply increase. Reminder, the current supply chain is now flush with heavily tariffed inventory, so expect prices to continue to increase over the next few months, regardless of surcharges.
*If any of your products contain tungsten, expect immediate and severe price hikes due to Chinese supply controls (war).
*Copper market entering severe supply shortages, expect low inventories and high prices.
LEAD TIMES: Domestic steel capacity is insufficient to fulfill US demand in any market. Lead times are, as expected, mixed, but soon will change (for the worst):
- USA mills lead times are pushing out, some products nearing 65 weeks.
- Foreign mill capacity is starting to fill. We expect supply to tighten once the EU's new reduced quota and increased tariff policy on Asian steel is implemented this summer.
BASE PRICES: Recent USA price increases remain in effect, and we expect them to hold given extended lead times.
SECTION 232: JUNE 4TH - 50% TARIFF applied to all imported copper, steel, and aluminum. Quotas and exemptions were eliminated. Reciprocal tariffs do not apply to good accessed Section 232 Tariffs.
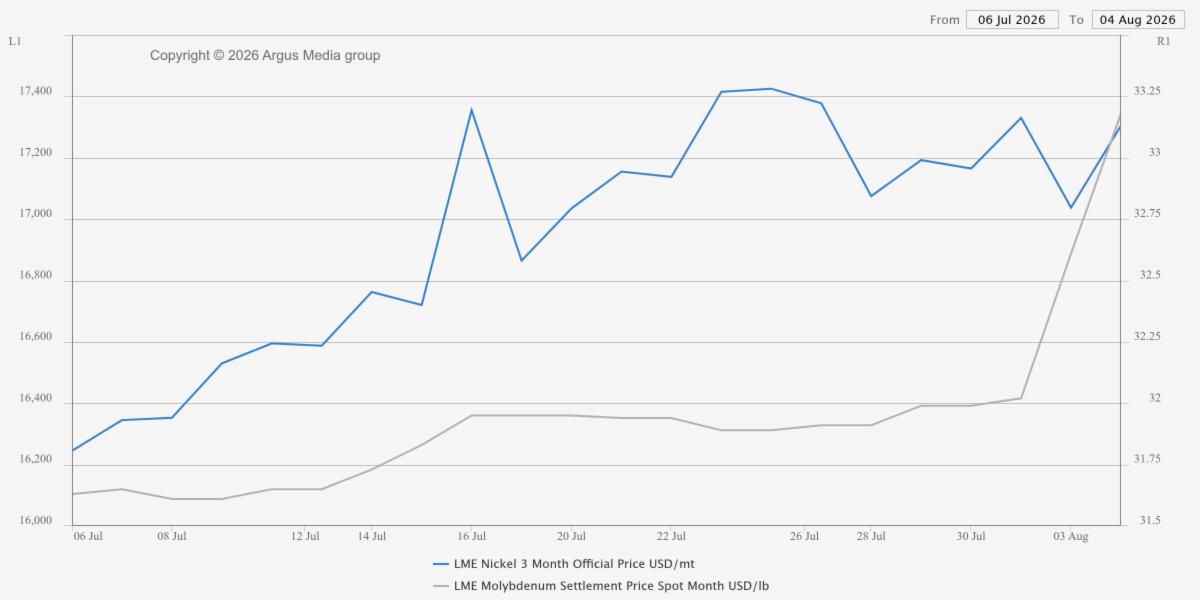
1 MONTH LME Nickel Cash v LME Moly Spot (top)
6 MONTH LME Nickel Cash v NYMEX Oil (middle)
1 YEAR LME Moly Spot v Nickel v Chrome (bottom)
Copyright (c) 2026 Argus Media Group
Industry News